There are plenty of firms offering investment management and financial advice, and for someone with meaningful savings or retirement funds, choosing who to trust with your money is a major decision. Yet it can be surprisingly difficult to work out what separates one adviser or investment company from another.
A polished website, a reassuring office and a confident adviser can all create a good first impression, but choosing someone to manage or advise on your investments requires a little more digging. The right questions can reveal how a firm operates, how it is paid and, perhaps most importantly, whether its approach fits your circumstances and expectations.
Start with the adviser
Before discussing investments, find out who you will actually be dealing with. What qualifications and experience do they have? How long have they been providing financial advice, and what sort of clients do they typically work with? Someone helping clients build wealth over several decades may have a different area of expertise from an adviser who primarily works with people approaching retirement.
In New Zealand, financial advisers must meet regulatory requirements, and you can check whether an adviser or business is registered and licensed to provide financial advice. It is worth doing this independently rather than relying solely on information provided by the firm. Registration does not tell you whether an adviser is right for you, but it is an important starting point.
Ask how they are paid
Money is an unavoidable part of the conversation, so don’t be uncomfortable asking exactly how the adviser and company make their money. You should be able to understand the fees involved before making any commitment.
Some advisers charge a fee for their advice, while others may receive commissions or have arrangements with investment providers. There can also be ongoing management fees, administration charges and other costs associated with the investments themselves. A percentage-based fee can sound small, but over many years even a relatively modest annual charge can make a substantial difference to the amount remaining in your portfolio.
Ask for the costs in dollars as well as percentages where possible. It is much easier to assess a 1 per cent annual fee when you understand what it means on a $300,000 portfolio than when it appears simply as a percentage on a document.
Find out how independent the advice is
An important question concerns the range of investments an adviser can recommend. Does the firm consider investments from across the market, or does it mainly recommend products managed or supplied by its own organisation or associated companies?
There is nothing inherently wrong with a firm having its own investment products, but you should understand the relationship. Ask why a particular investment has been recommended and whether comparable alternatives were considered. A good adviser should be able to explain the reasoning in terms you can understand, rather than simply telling you a particular product is suitable.
Understand what you are actually paying for
Financial advice can mean quite different things depending on the firm. One adviser might provide a plan and investment recommendations, leaving you to make the final decisions. Another may manage your portfolio on an ongoing basis, review your circumstances regularly and make changes within an agreed framework.
Ask what the service includes and how often you can expect contact. Will you have an annual review? Can you call when something changes in your circumstances? Will the adviser help you consider how your investments fit alongside other retirement income, savings or major financial decisions?
It is also worth asking who makes the investment decisions. Will you approve every change, or are you giving the adviser authority to manage the portfolio on your behalf? Neither arrangement is automatically better, but you should be comfortable with the level of control you are handing over.
Ask where your money is held
An adviser may recommend or manage your investments, but this does not necessarily mean the adviser personally holds your money. Ask where your investments and cash will be held, which organisation provides custody or administration, and what protections and reporting arrangements apply. Understanding the different roles can provide considerable reassurance. You want to know who is giving the advice, who is managing the investments, who is holding the assets and who you contact if something goes wrong.
Talk about difficult markets
One of the most revealing conversations you can have with a prospective adviser may involve what happens when investments fall. Rather than asking only about expected returns, ask how the firm approaches periods of market volatility. How would they communicate with you during a significant downturn? What might cause them to recommend changing your investments? How would they balance the need for growth against your need for accessible income?
There is no adviser who can predict every market movement, and promises of consistently high returns should make you cautious. A sensible discussion about risk should include the possibility of losses, the length of time you expect to invest and how much fluctuation you can realistically tolerate.
Trust your questions as well as your instincts
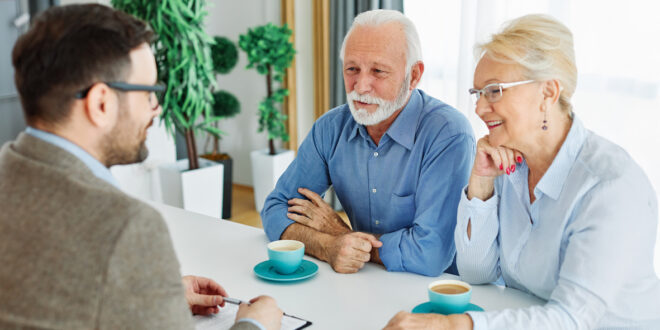
A first meeting should feel like an opportunity to ask questions, not a sales presentation. You should be able to say you need time to think, take the information home and compare your options without feeling pressured to make a decision.
Pay attention to how the adviser responds when you ask something they may not have expected. Do they explain things patiently? Are they willing to acknowledge uncertainty? Do they ask about your circumstances before recommending a solution?
Perhaps the simplest test is whether you understand what you are being offered. Investment advice does not need to be complicated simply because investing can be complicated. If you leave a meeting unable to explain what the adviser will do, what it will cost or where your money will be invested, it may be worth having another conversation before proceeding.
Choosing a financial adviser is ultimately about more than finding someone who appears knowledgeable. You are establishing a relationship around some of your most important financial decisions, potentially for many years. Taking time to compare advisers, understand their fees, investigate their approach and ask uncomfortable questions at the beginning can make it much easier to decide who deserves your confidence.
Join the Discussion
Type out your comment here:
You must be logged in to post a comment.